Analyse de marché

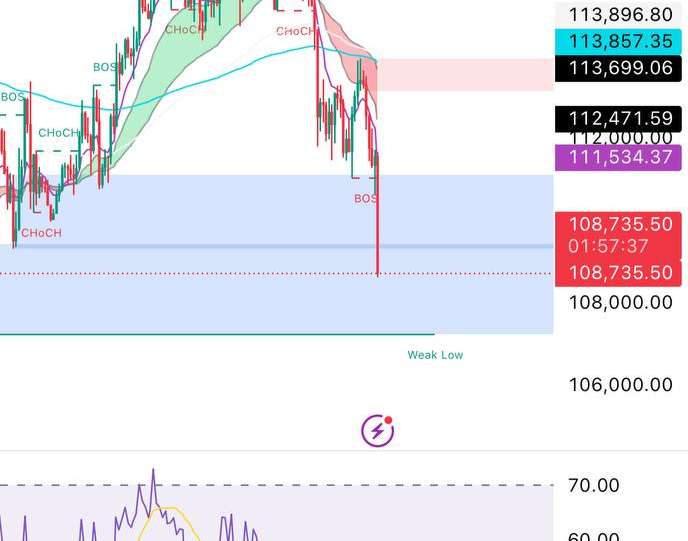
Gold fell below USD 4,000/oz (USD 3,990–3,996 on October 27), declining by more than 20% from its January 2026 all-time high (above USD 5,400) and ending 2026 down 7.5%, alongside Bitcoin (-7.3%), with both assets ranking last among major asset classes.
This configuration is historically unprecedented: it is the first time a calendar year has ended with both gold and Bitcoin simultaneously underperforming equities, bonds, and cash. The hedging regime underpinning our strategic allocation has changed.
The question, therefore, is not whether gold is a “good” or “bad” asset, but whether the hedging function attributed to it remains effective under the current macroeconomic and market microstructure regime.
The diagnosis is unambiguous: gold has not failed as a long-term store of value; it has failed as a tactical liquidity hedge in a regime where real-rate repression and competition from high-yielding Treasuries dominate flow dynamics.
Gold’s decline is the result of four converging forces: (i) a hawkish repricing of the Fed’s rate path (probability of a December rate hike ≈ 86%); (ii) the oil shock following the escalation in the Strait of Hormuz (Brent > USD 112), which fuels inflation and keeps real rates firmly in positive territory; (iii) rotation into Treasuries as yield-bearing safe-haven assets (4–5%), capturing hedging demand at gold’s expense, as gold generates no yield; (iv) ETF outflows and forced liquidations of long positions accumulated during the 2025 rally (+63.7%), creating a self-reinforcing downward dynamic.
Strategic implication: physical gold hedging must be reassessed, resized, and supplemented, not simply abandoned. Physical gold remains a reserve asset of last resort against sovereign balance-sheet risks and monetary debasement, but it is not a reliable tactical hedge against a crypto liquidity crash.