Title: The tokenized real-world asset market has fundamentally changed. It’s no longer a bet on token appreciation: it has become a cash flow engine, rents, interest, coupons distributed automatically via smart contract. Analysis of a paradigm shift. In 2021, tokenization evoked speculative art NFTs. In August 2026, it evokes something else: ~$34.5 billion in tokenized assets, including ~$15 billion in US Treasury bonds spread across 76 products and nearly 58,700 holders. The market’s core is no longer the profile picture, it’s the coupon.
1. The new paradigm: value through cash flow, not multiples. An RWA investor’s reasoning now resembles that of a bond buyer: what is the underlying asset’s cash flow, how regular is it, who guarantees it, and how is it distributed? A tokenized Treasury yields US monetary returns; tokenized private credit (8 to 18.9 billion dollars in assets depending on methodology, 33.7 billion dollars originated in total) generates interest from real-world borrowers; a tokenized building generates rental income. Speculation on the token price becomes secondary: value is derived from the distributed yield, automated by smart contracts, scheduled payments, no payment intermediaries, traceable on-chain.
2. Why institutionalization follows the rent. BlackRock did not venture into NFTs: BUIDL, its tokenized money market fund, stands at approximately $2.6 billion and now serves as reference collateral in DeFi and CeFi (Ethena’s USDtb reserves, Sky/MakerDAO allocators, margin at FalconX). When the most institutional on-chain asset is a cash fund, the message is clear: the winning RWA is the one that resembles fixed income, not the one that resembles a collectible.
3. What automated distribution changes. In traditional private credit, interest distribution requires a paying agent, a registrar, and reconciliations. On-chain, the smart contract handles: coupon calculation, pro-rata distribution to holders, stablecoin payments, and an immutable audit trail. Administrative costs collapse, granularity increases (weekly or even daily payments become economically viable), and transparency becomes native, every investor can verify the source of the flow.
4. The three risks that the annuity does not eliminate. (a) Credit risk: the token does not improve the borrower; default remains default. (b) Structural risk: much of “tokenized real estate” consists of SPV shares, the legal chain from SPV to token must be flawless. (c) Rail risk: the annuity is paid in stablecoins, a market 83% concentrated in two issuers and now regulated (GENIUS Act in the United States, MiCA in Europe), the quality of the distribution rail becomes a standalone investment criterion.
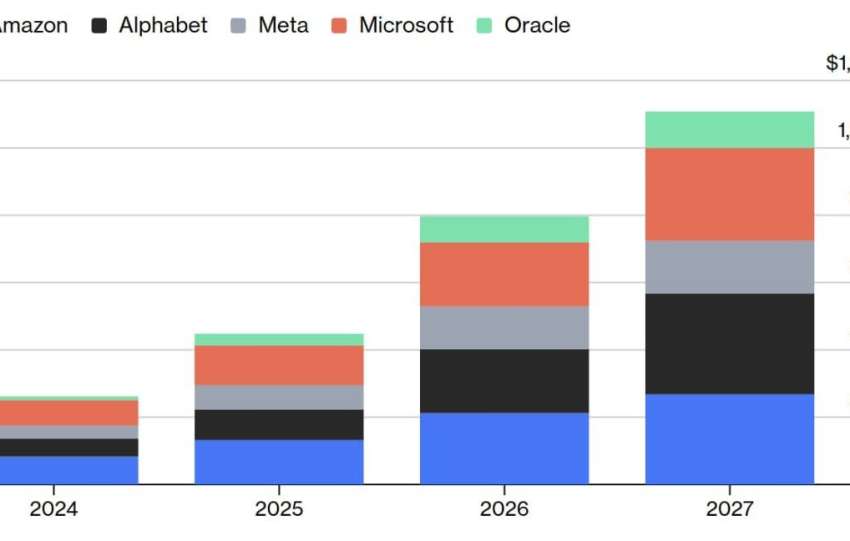
Conclusion: The projections for 2030 range from $2 trillion (McKinsey) to $16 trillion (BCG, high adoption scenario). In both cases, the products that will capture this flow will not be the most speculative: they will be the most transparent, stable cash flows, automated distribution, documented compliance. The era of RWA-annuity has begun. It will be measured in basis points of yield, not in multiples of hype.