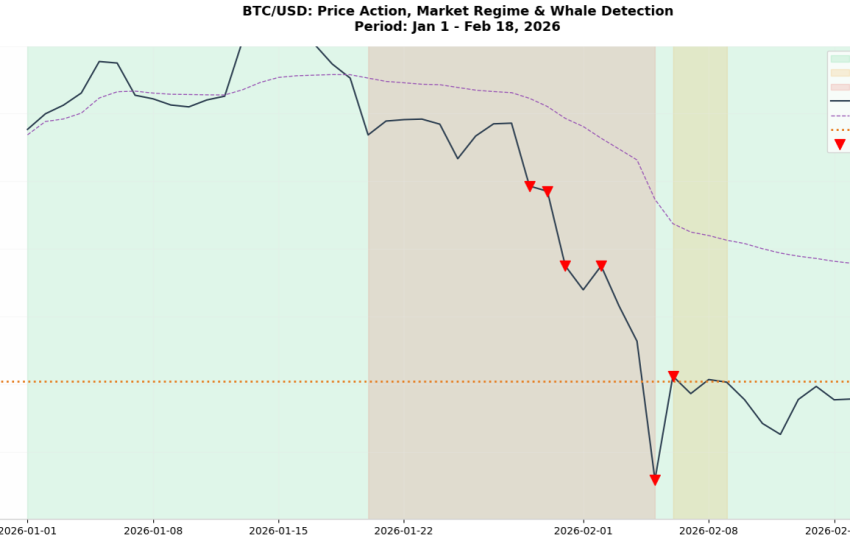
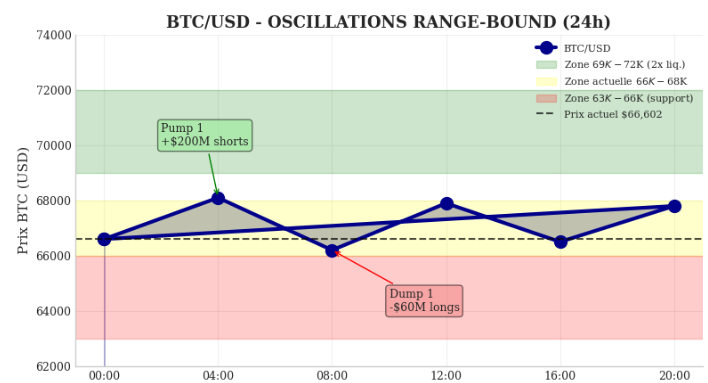
The market is no longer in capitulation (June–July, Bitcoin below $60–63k) nor in a confirmed breakout. It is in an institutional range regime after an August rally (~+20–25% on BTC since summer lows) and repeated failure below $82,000. Alts have outperformed BTC over 30 days (XRP / Solana ~+35–36%, Ethereum ~+30%, BTC ~+21%), then leverage shifted toward alts (alt perpetual OI > BTC OI in early September, first time since late 2024). ZEC was the most extreme vector (surge above $1,000, OI up to $2.4B, OI up to ~$2.4B, OI up to $2.4B, then unwind).
Two event-risk catalysts this week:
1. Senate CLARITY Act vote. Republicans published a “final” text incorporating ethics clauses; prediction markets raised odds of 2026 passage (on the order of ~30% according to some sources, still far from a base case). A failed vote likely buries the text for 2026.
2. FOMC Sept. 15–16. Current range 3.50–3.75%. After Jackson Hole (Warsh) and elevated oil, probabilities of a 25 bp hike have been significantly revised upward (often cited at 60–70% depending on the window). August CPI has barely repriced the path; the crypto market has held the range.
Flows. Intra-crypto rotation rather than gross outflows:
¤ Spot BTC ETFs saw recent outflows (several hundred million USD over Sept. 8–11) while remaining positive for the month; ETH ETFs saw inflows (including one strong day ~$216M);
¤ SOL/XRP flows smaller but often positive. BTC ETF AUM still ~$97–98B.
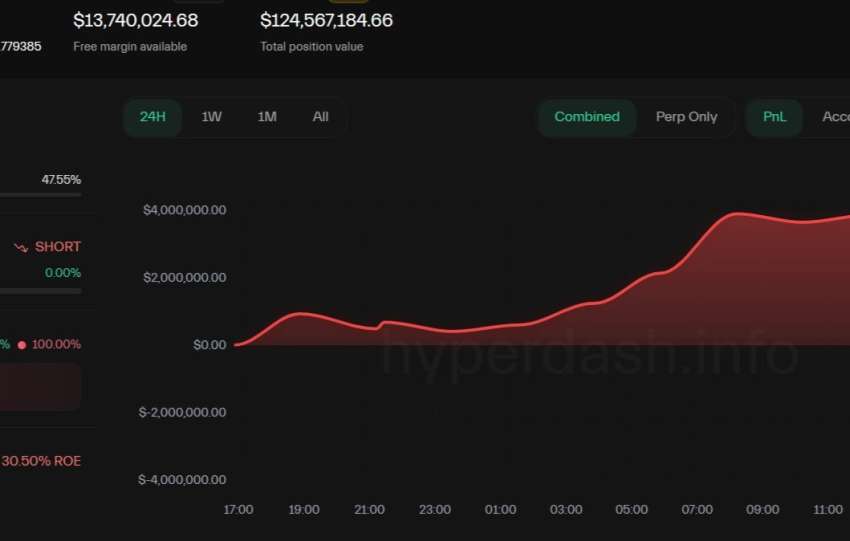
Microstructure. BTC/ETH perpetual funding positive but not extreme; ZEC flipped to negative funding during the unwind. Long/short ratio on BTC accounts near balance. Main cascade risk: alt leverage (ZEC, HYPE, XRP) if BTC breaks $76k and the FOMC is hawkish.
BTC. Liquidity Anchor
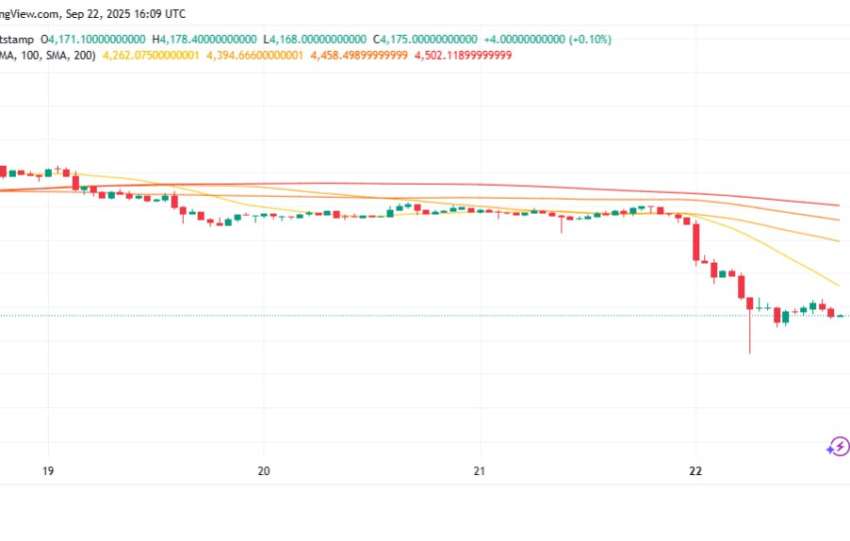
Price/Structure: $77.1k–$77.8k, volume support ~$76k–$77.1k (May breakout level and 2026 highest volume per several desks), resistance $78k–$79k then $80k–$82.3k (double failure in May and Sept 3–6, high ~$82.2k–$82.3k). ~38% below 2025 ATH. Daily RSI ~55–56. 50-DMA above spot; weekly trend still constructive as long as $76k holds.
Flow Fundamentals: Corporate treasuries still substantial; ETFs = absorption channel for new supply, but August inflow streak has paused. Dominance ~59% = risk-selective environment, not broad altseason.
CME COT (Sept 8, futures only, partial reading): CME BTC OI ~21.5k contracts (5 BTC contract); non-commercials and leveraged funds do not show a classic extreme short squeeze. Micro BTC OI much broader (retail/prop). COT signal: neutral to slightly cautious, not a crowded long of 2024–25.
Bias: Range-bound with bearish asymmetry if double regulatory + monetary failure. The volume vacuum $81.3k–$86.5k remains the upside if weekly close > $82k.
ZEC, idiosyncratic regime (privacy + ETF + squeeze)
Price: ~$1,135–1,140 after a 25x run over 12 months, top 10 market cap ($18–19B), privacy sector ~$33B with ZEC ~60%+ share. First US spot privacy ETF (Grayscale ZCSH conversion, August 25); AUM cited ~$400–460M in two weeks.
Ironwood upgrade / shielded pool; governance polls on September 14, 19:00 UTC. All-time high from 2016 ~$3,192 still far off.
Micro: Record OI ~$2.4B then unwind ~20% (OI toward ~$1.4B), short liquidations then reversal; negative funding = shorts paying, but crowding has already been partially flushed.
Read: This is no longer an orphan coin. It’s a narrative + ETF flow + leverage asset. Convexity remains high in both directions. A post-squeeze fade is statistically more common than a linear continuation toward $2,000 without new flows.