The convergence that no one predicted, except upon closer inspection This is where history meets programmable finance. MiCA, fully applicable since July 1, 2026, after the end of the transitional period, licenses the European crypto perimeter. ISO 20022 standardizes the grammar of global payments. And certain blockchain networks, the XRP Ledger foremost, whose ODL corridors…
The tokenized RWA market totals ~$30-35B in AUM (rwa.xyz: ~$34.5B, ~2x year-over-year). Breakdown: Tokenized US Treasuries & money market funds ~$13.4-15.2B (76 products, ~58,700 holders; top names BUIDL ~$2.4-3.1B, USYC $2.9B, USDY ~$2.1B, BENJI $2.05B); private credit $8-18.9B depending on scope, $33.7B in cumulative originations; commodities (mostly gold) ~$5.5B with XAUT+PAXG >96% of the segment…
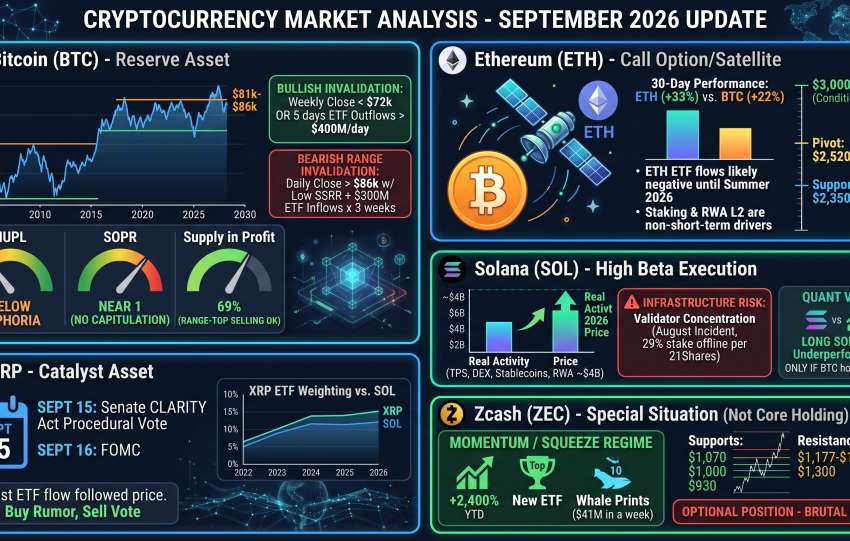
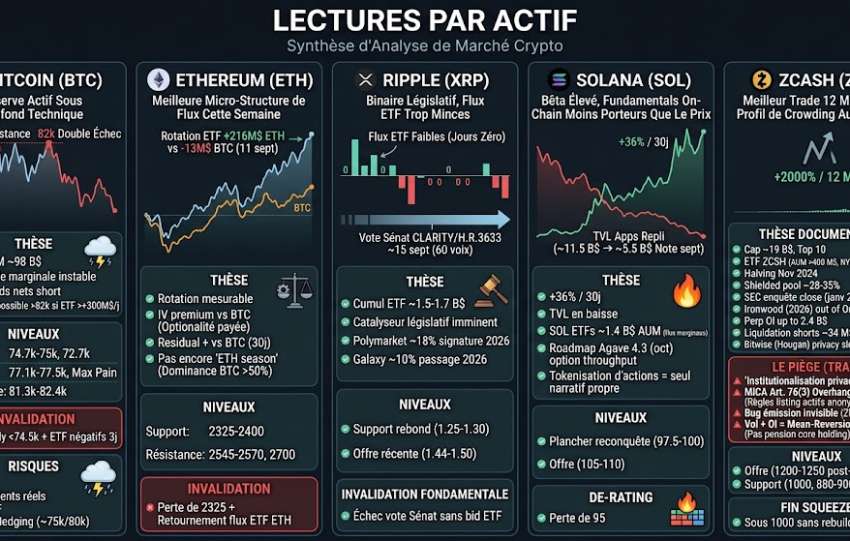
Bitcoin remains a reserve asset with a structure showing recovery from $58-62k, rejection under $81-86k, and consolidation around $77k. NUPL is below euphoria, SOPR near 1 (no capitulation or aggressive distribution), and 69% of supply is in profit—enough for range-top selling but insufficient for a blow-off. Bullish invalidation: weekly close below $72k or 5 days…
The framework is a two-regime Markov model with observable states, not a calibrated HMM
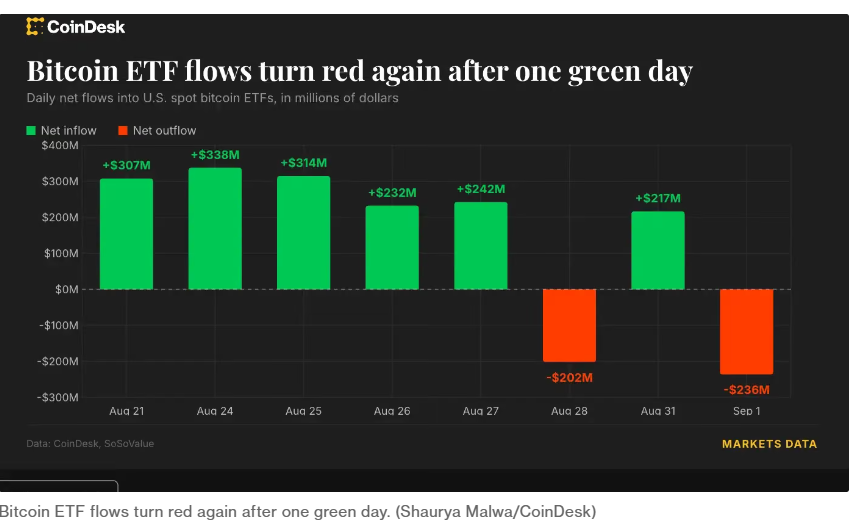
Regime 1 (Liquidity risk-on) is indicated by positive 5-day net $BTC / $ETH ETF flows, declining $DXY, funding below 0.03% per 8 hours, and BTC above 77.1k then 81.3k.
It implies overweighting ETH/ $SOL relative to BTC, with only reduced $ZEC…
Thesis. Raw materials are regaining a core portfolio role (hedging a multipolar world and AI electrification), while European ESG shifts from an obligation-based regime to a market-driven one, less reporting, more pricing. Key Data. January 2026 records: gold ~$5,405/oz (2025 annual average: $3,431, +44%), silver >$121/oz, LME copper $13,238/t. Citi scenarios (Q3 2026): Brent…
Thesis. The European Omnibus did not kill ESG: it transformed it from a mass legal obligation into a competitive market advantage. Demand for reliable ESG data is shifting from the regulator to the investor, the bank, and the buyer and ESG ratings themselves are now under supervision.
The new regime (Directive (EU) 2026/470, in…
The macro regime as of September 2, 2026, shows a strong U.S. dollar (DXY at ~99.73-99.80) and rising 10-year U.S. Treasury yields (4.78-4.81%), pressuring risk assets. An oil supply shock (Brent ~$95.3, WTI ($4,290-4,325/oz) is declining due to real yields and dollar strength. A Hidden Markov Model (HMM) identifies the current regime as "Transition"…
The dominant factor in September is not an endogenous crypto narrative but a regime of real rates and geopolitical energy premiums.
US 10-year yields hit ~4.76-4.78%, the highest since January 2025, while the #DXY traded around 99.45-99.50.
Oil prices (WTI ~$86.5) reacted to US-Iran tensions and the Strait of Hormuz.
The Fed funds target is…
The market has exited the capitulation phase of June 2026, where BTC fell below $60k, driven by ETF creations and short squeezes pushing prices to ~$81.3k, though this does not confirm a sustained bullish cycle. Three simultaneous frictions are identified: a BTC supply wall between $81k-$86k, a potential 25bp hike at the September FOMC meeting…
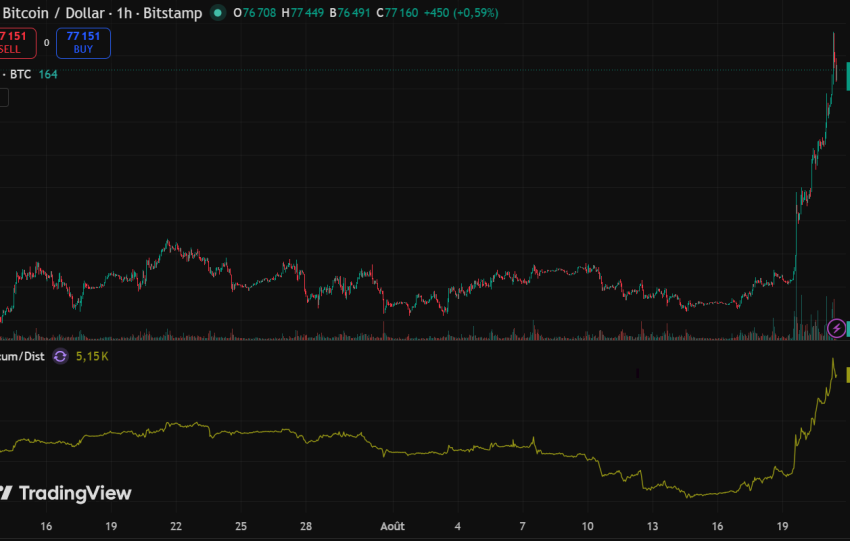
Bitcoin surged to $76,800-$77,600, gaining 6-8% in 24 hours and 20% for the week. The market saw over $4 billion in 24-hour liquidations, marking the most violent short squeeze of 2026. Combined BTC/ETH ETF inflows exceeded $800 million, indicating massive institutional entries. The funding rate shifted from negative to positive, signaling a return of long…
Analyse de marché
Carbon Credit Market