Analyse de marché

Impact of the Iran conflict and rising energy prices on gold price dynamics and the state of the mining sector. The views of Chris Mancini, co-portfolio manager of the Gabelli Gold Fund (GOLDX), are based on an analysis of current economic conditions and expectations ahead of the release of third-quarter earnings reports.
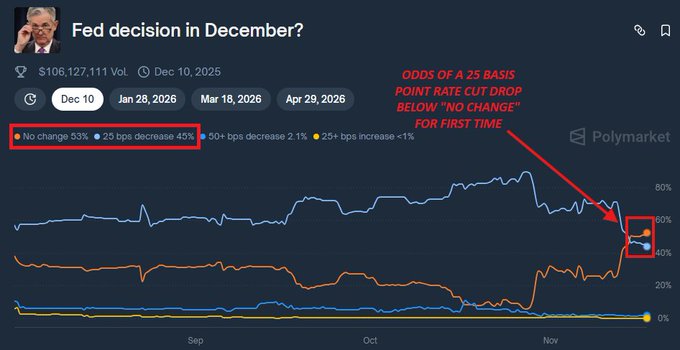
The conflict involving Iran and disruptions to oil supplies through the Strait of Hormuz have created unfavorable conditions for gold: rising energy prices fuel inflation and increase expectations of Federal Reserve interest rate hikes, negatively affecting gold prices. If the situation had been resolved over the summer, gold would likely have already reached $5,000. The conflict is merely delaying gold’s inevitable rise to $5,000.
Mining companies remain in a strong position thanks to historically high metal prices. Strong earnings and significant free cash flow are expected for the third quarter, although some figures may fall below consensus forecasts due to rising energy and labor costs. The increase in labor costs is partly driven by a pickup in development activity as gold prices approach $4,000 per ounce.
Unlike the bull market of the early 2010s, companies today are opting for more manageable projects requiring less capital investment and demonstrating greater capital discipline.
Gold mining stocks continue to struggle to attract a broad investor base because of skepticism about the sustainability of high gold prices. A sustained recovery in gold prices could be the first step toward attracting investors. Mancini believes that increasing dividends, rather than buying back shares, would be more effective in attracting investors. For example, Newmont (with a market capitalization of approximately $120 billion) could allocate $8 billion to share buybacks and $1 billion to dividends, but investors focus only on the dividend yield. An 8% dividend yield would attract attention. Higher dividends would help mining stocks stand out against physical gold, which generates no income in a high-interest-rate environment.
The timing of the next significant rise in gold prices remains uncertain. The labor market could be an important catalyst: if the October report shows a decline of 100,000 in US economy employment, gold prices could surge.
Conclusions
The conflict involving Iran is a temporary obstacle rather than a fundamental threat to gold’s long-term prospects; the mining sector continues to generate substantial cash flows, but mining stocks remain undervalued and need to attract a broader investor base by increasing dividend yields.