Analyse de marché

The hypothesis is that crypto flows become a significant channel for High Net Worth Individuals (HNWI) leaving the UAE. The core issue is that direct capital flow data is unobservable, and all available proxies (e.g., exchange volume, on-chain data, stablecoin supply, real estate sales, surveys, suspicious activity reports) suffer from significant biases. These proxies measure related activities like trading or local hedging, but not pure outflows, and often lack precise geolocation or conflate different financial behaviors. The methodological conclusion is that with open data from September 2026, it is impossible to quantify a specific “UAE crypto outflow” in billions. Instead, the hypothesis can only be tested by examining and attempting to falsify its observable implications.
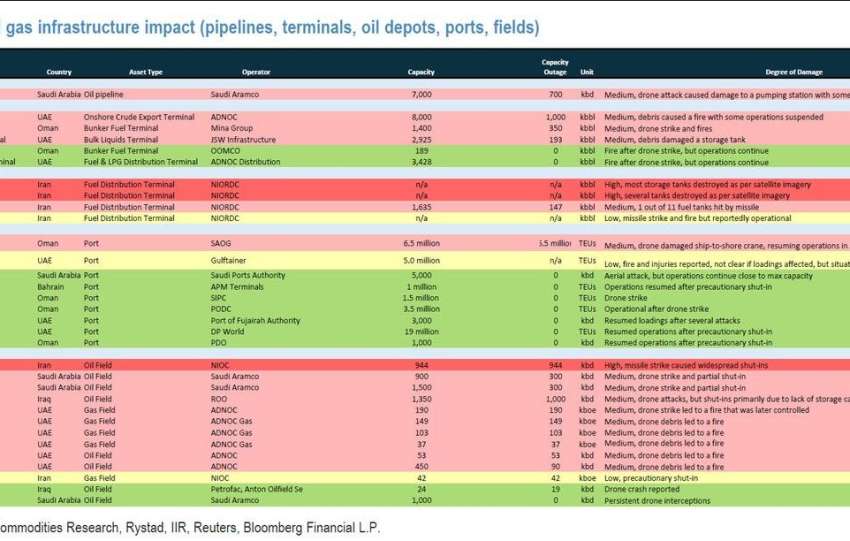
The conflict since February 28, 2026, is a US/Israel-Iran war extending into the Gulf, with strikes on Hormuz traffic, war-risk coverage withdrawal, tanker attacks, and Iranian retaliation against GCC targets including the UAE. On September 18, 2026, Iran claimed a strike/detention of a Togolese tanker in the Strait; Brent ~$104, Murban ~$121. The UAE is not a main belligerent but is in the economic blast radius: aviation, tourism, real estate, marine insurance, and implicit sovereign risk premium. This frames a safe-haven shock model: an asset (Dubai-as-haven) sees its safety parameter s drop, raising required return r + λ(s).
A theoretical framework is presented for analyzing the portfolio behavior of a High-Net-Worth Individual (HNWI) based in Dubai under geopolitical stress. The HNWI maximizes a utility function considering expected returns, risk aversion, and illiquidity costs. A geopolitical shock, such as a Gulf War, is modeled using a two-regime Hidden Markov Model, increasing the variance of UAE assets (real estate, local equities, tourism earnings) and correlations within the Gulf region.
Crucially, the optimal response is not a simple “sell everything for USDT.” Due to the illiquidity of assets like off-plan properties and villas, the immediate observed effect is a transaction freeze rather than a crypto outflow. The dirham’s peg to the USD prevents a classic currency crisis, and the UAE’s lack of capital controls (unlike China or India) means crypto is not the only channel; SWIFT, private banking, family offices in Singapore/Hong Kong, and custodians in DIFC/ADGM remain open. Therefore, the primary hypothesis (H1) of a direct crypto haven flow is likely not the modal channel. The modal response to a haven shock involves: (i) stopping new investments, (ii) lengthening property sale timelines, (iii) scouting alternative residences, and (iv) reallocating books toward USD cash, Treasuries, or Singapore, often off-chain.
Cryptocurrency is framed as a real option for exit, valued based on on-chain wealth net of fiat conversion costs (banking delays) and AML risk (freezing, Travel Rule, VARA, CBUAE, OFAC sanctions). Since 2025-2026, AML risk in the UAE has increased with quarterly VARA guidance, Travel Rule implementation, new AML laws for VASPs, and penalties up to 1 billion AED. For compliant family offices, this high AML risk makes crypto less attractive as a flight vehicle compared to informal actors, contradicting the common narrative of mass “USDT exits.”
Our analysis critically distinguishes between four distinct capital flows to avoid a meaningless study:
1. Flight-to-safety (HNWI): Selling Dubai assets to hold USD/SGD/CHF elsewhere.
2. Local hedging: Residents buying BTC/USDT on local exchanges, increasing CEX volume without an outflow.
3. Hub activity: The UAE acting as a central hub (VARA, ADGM, Binance FZE, OKX ME, Standard Chartered spot BTC/ETH), drawing inflows into the UAE.
4. Sanctions/oil (Iran): Using USDT/Binance for Iranian oil revenues (e.g., a Sept. 2026 DOJ complaint citing ~$1.5B to Iran-linked wallets), which represents a flow to Iran, not an outflow from Dubai. Confusing flows 2, 3, and 4 with flow 1 creates the illusion of a “Dubai outflow.
Dubai’s real estate market is experiencing a significant volume shock, not a generalized price crash. Knight Frank reports residential transactions fell 13.6% year-on-year in H1 2026, with sharp drops in May (−45%) and June (−16.4%). CBRE data shows Q2 2026 transactions below 37,000, down 29% YoY, though prices still rose 1.9% YoY. Goldman Sachs notes UAE volumes fell 37% YoY in early March and 49% versus February. Secondary ready properties show apartments down 37% and villas down 29% post-conflict versus 2025. Flippers are exiting or freezing, sellers refuse to cut prices, so inventory isn’t converting to crypto outflows.
The stock isn’t turning into USDT because closings are plummeting. Micro-cases like wealthy Pakistanis repatriating to Karachi via remittances (+13% Feb–Aug, +36% in May) show fiat corridors, not on-chain evidence. GCC equity outflows in July 2026 were approximately $415 million, but the UAE lost only $26 million net, the lowest in the Gulf. Internal rotation shows Abu Dhabi gaining +$148 million while Dubai lost $174 million, indicating flight to the safer sovereign node within the federation, not a mass exit. High-net-worth mobility shows intentions rather than on-chain liquidation: New World Wealth expects UAE net HNWI outflows in 2026 despite being the top post-Covid magnet; Henley reports residency applications down 13% Q1 2026; Capgemini notes HNWI wealth in the Middle East already down 1.5% in 2025; NYT reports wealthy Asians exploring Singapore/HK with one lawyer citing 6–7 calls from 20 Dubai clients ($50M each).
Short-term departures include ~30k Britons and >52k Indians since the war, but institutional books show resilience: Mashreq Private Bank calls outflow fears “exaggerated” with its best year in 5, while PWM/Klay Group states data doesn’t support capital-flight narrative, with DIFC growing 22% to >500 asset managers. Henley ranks UAE #2 globally for crypto adoption (10/10 tax), St James’s Place survey shows 44% planning retirement there, and Saudi family office Juffali moved from London to Dubai despite the war. The real damage is to the real economy: tourism arrivals dropped 38% (worst than 11–27% scenarios), hotel occupancy down 29% over 7 months, representing service flow destruction rather than crypto transfers. Crypto-specific data shows the UAE received over $56 billion during 2024–25 (+33% YoY), local payment volumes in Q1 2026 exceeded all of 2024 by 30×, with USDT dominating at 72% of transactions. Institutionalization continues with Standard Chartered launching institutional spot BTC/ETH, VARA-Securitize tokenized markets, and FAB-Citi tokenized deposits via Swift. Tighter AML regulation includes VARA’s quarterly risk assessments, Travel Rule enforcement, and CBUAE licensing with fines up to AED 1 billion. June’s $4.2 billion global crypto outflows concentrated in US ETFs, and CEX netflows of −$5.4 billion aren’t UAE-specific. The documented Iranian flow goes inbound—two Chinese firms laundered $1.5 billion from Iranian oil via Binance, representing sanctions evasion into Iran, not UAE HNWI outbound flows. Overall assessment: The data shows a significant disruption in Dubai’s real estate volume, a regional rotation within the UAE to Abu Dhabi, anecdotal HNWI scouting and intention surveys, a tourism collapse, and a thriving local crypto ecosystem with tightening regulation. However, there is no measurable evidence of a large-scale institutional “wealth book” liquidation through on-chain channels. The narrative of capital flight appears exaggerated; what exists is an attractiveness shock, short-term departures, and a genuine shift to safer regional nodes, but institutional infrastructure continues to grow, and crypto adoption is strengthening domestically.